
Europa Industria: A Comprehensive Guide to European Industrial Landscape, Trends, and Future Outlook
—
Introduction: Why European Industry Matters More Than Ever
Europe’s industrial sector stands at a defining crossroads. With manufacturing output contributing approximately €2.3 trillion annually to the European economy and employing more than 30 million people across the continent, the industrial landscape of Europe — often referred to collectively as Europa Industria — represents one of the most complex, innovative, and strategically vital economic ecosystems in the world.
From the precision engineering workshops of Germany’s Mittelstand to the aerospace clusters of Toulouse, from the automotive powerhouses of northern Italy to the green energy manufacturing hubs emerging across Scandinavia, European industry is not a monolithic entity. It is a richly diverse, deeply interconnected network of sectors, companies, policies, and people that collectively shape global supply chains, set international standards, and drive technological advancement.
This comprehensive guide explores the full spectrum of Europa Industria — its historical foundations, current structure, major sectors, policy environment, digital transformation, sustainability challenges, and the strategic roadmap for its future. Whether you are a business leader, policy analyst, investor, or simply a curious reader, this article provides the authoritative insight you need to understand European industry today.
—

The Historical Foundations of European Industry
The Industrial Revolution and Its European Legacy
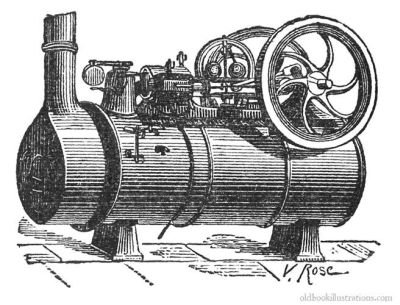
Europe did not simply participate in the Industrial Revolution — it invented it. Beginning in Britain in the late 18th century and spreading rapidly to Belgium, France, Germany, and beyond, industrialization fundamentally transformed European societies, economies, and geographies. The development of steam power, mechanized textile production, iron and steel manufacturing, and railway networks created the foundational infrastructure upon which modern European industry still operates.
By the early 20th century, Europe was home to the world’s most advanced industrial economies. Germany’s chemical and engineering industries, Britain’s shipbuilding and textile sectors, France’s luxury goods and automotive manufacturing, and Belgium’s coal and steel production all contributed to a continent that dominated global industrial output.
Post-War Reconstruction and Industrial Policy
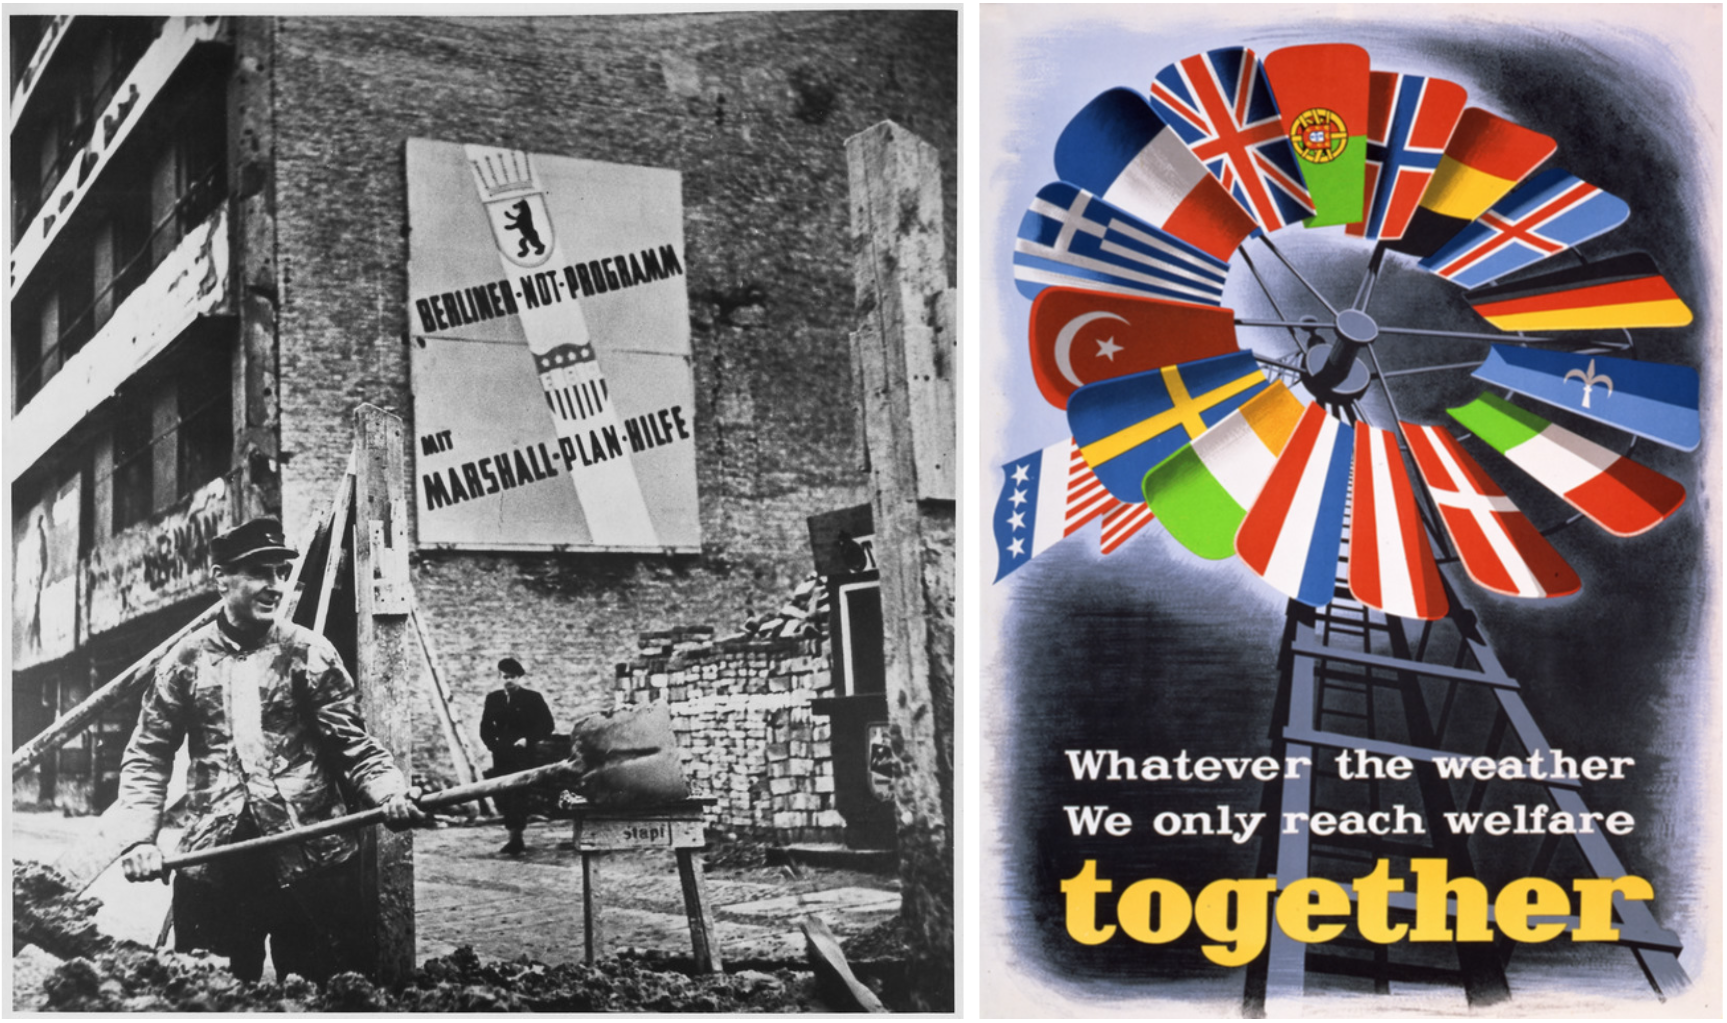
The devastation of two World Wars forced Europe to rebuild its industrial base from the ground up. The Marshall Plan, implemented between 1948 and 1952, injected critical investment into European manufacturing infrastructure. More significantly, the founding of the European Coal and Steel Community (ECSC) in 1951 — the direct precursor to the European Union — represented a landmark moment in which European nations chose economic cooperation over industrial competition as a strategic framework.
This decision to integrate industrial policy at a supranational level has had profound and lasting consequences for how European industry operates today.

The Rise of the European Single Market
The creation of the European Single Market in 1993 eliminated tariff barriers, harmonized regulations, and created a unified trading area of unprecedented scale. For European industry, this meant access to a market of over 450 million consumers, free movement of goods and capital, and the ability to build pan-European supply chains that dramatically increased efficiency and competitiveness.
The Single Market remains the single most important structural advantage that European industry possesses — a fact that becomes increasingly evident when comparing European industrial performance against fragmented regional economies elsewhere in the world.
—
The Structure of Europa Industria Today
Key Industrial Sectors Driving European Economic Output
European industry today is organized across several major sectors, each with distinct characteristics, competitive dynamics, and strategic priorities.
Automotive Manufacturing
The European automotive industry is one of the continent’s crown jewels. With manufacturers including Volkswagen Group, Stellantis, BMW, Mercedes-Benz, Renault, and Volvo, Europe produces approximately 12 million vehicles per year, representing roughly 20% of global automotive output. The sector directly employs 2.6 million people and supports an additional 10 million jobs in the broader supply chain.
Germany remains the undisputed center of European automotive manufacturing, but significant production clusters exist in Spain, France, the Czech Republic, Slovakia, and Hungary. The industry is currently undergoing its most dramatic transformation since the invention of the internal combustion engine, driven by the transition to electric vehicles (EVs) and the digitalization of vehicle systems.
Aerospace and Defense
Europe’s aerospace sector is a global leader, anchored by the Airbus consortium and supported by a vast ecosystem of tier-one and tier-two suppliers. The European aerospace and defense industry generates revenues exceeding €250 billion annually and employs approximately 900,000 people across countries including France, Germany, the United Kingdom, Spain, and Italy.
The Toulouse-Bordeaux corridor in France, the Hamburg aerospace cluster in Germany, and the Bristol aerospace hub in the UK represent some of the world’s most sophisticated industrial concentrations. Alongside commercial aviation, European defense manufacturing has gained renewed strategic importance in the context of geopolitical tensions in Eastern Europe.
Pharmaceuticals and Life Sciences
The European pharmaceutical industry is a global powerhouse, home to companies such as Roche, Novartis, AstraZeneca, Bayer, Sanofi, and UCB. Europe accounts for approximately 25% of global pharmaceutical production and is the world’s largest exporter of pharmaceutical products.
Switzerland, while not an EU member, is integral to the European pharmaceutical ecosystem. Germany, Ireland, Belgium, and the UK are also major pharmaceutical manufacturing hubs. The COVID-19 pandemic highlighted both the strategic importance and the vulnerabilities of European pharmaceutical supply chains, accelerating significant policy changes around production localization and supply chain resilience.
Chemical Industry
The European chemical industry is the second largest in the world, generating annual revenues of approximately €650 billion. Germany leads the sector, with BASF — headquartered in Ludwigshafen — being the world’s largest chemical company by revenue. Other major players include INEOS, Evonik, Covestro, and DSM.
The chemical industry serves as a critical upstream supplier to virtually every other industrial sector, from automotive and aerospace to agriculture and construction. Its transition toward green chemistry, bio-based feedstocks, and circular economy principles is one of the most significant industrial transformation stories in contemporary Europe.
Steel and Metals
European steel production, while significantly reduced from its post-war peak, remains strategically important. Companies such as ArcelorMittal, Thyssenkrupp, Salzgitter, and SSAB produce approximately 130 million tonnes of steel annually. The sector faces intense competitive pressure from lower-cost producers in Asia, combined with the enormous challenge of decarbonizing steel production — one of the most carbon-intensive industrial processes in existence.
Green steel production, using hydrogen-based direct reduction instead of coal-fired blast furnaces, is emerging as a transformative technology that could reposition European steel manufacturers as global leaders in sustainable metals production.
Food and Beverage Processing
Often overlooked in discussions of European industry, the food and beverage processing sector is actually the continent’s largest manufacturing sector by turnover, generating revenues exceeding €1.3 trillion annually. Companies ranging from Nestlé and Unilever to smaller regional producers form a complex ecosystem that links European agriculture with global consumer markets.
—
Industrial Policy and the Role of the European Union
The European Industrial Strategy
In March 2020, the European Commission published its updated European Industrial Strategy, setting out a comprehensive framework for maintaining and strengthening European industrial competitiveness in the face of global challenges. The strategy identifies three key objectives:
- Achieving climate neutrality by 2050 — aligning industrial production with the European Green Deal
- Ensuring digital leadership — accelerating the adoption of artificial intelligence, cloud computing, and advanced manufacturing technologies
- Building open strategic autonomy — reducing excessive dependencies on non-European suppliers for critical materials, technologies, and products
- Horizon Europe — The EU’s €95.5 billion research and innovation framework program (2021-2027), supporting industrial R&D across all major sectors
- InvestEU — A €372 billion investment mobilization program supporting sustainable infrastructure, innovation, and SME development
- Just Transition Fund — €17.5 billion dedicated to supporting industrial regions transitioning away from fossil fuel dependence
- Recovery and Resilience Facility — €723.8 billion in grants and loans supporting post-pandemic economic recovery, with significant industrial modernization components
- Predictive maintenance — AI algorithms analyzing sensor data to predict equipment failures before they occur, reducing unplanned downtime by up to 50%
- Quality control — Computer vision systems detecting defects with greater accuracy and consistency than human inspectors
- Supply chain optimization — Machine learning models optimizing inventory levels, logistics routing, and supplier selection
- Process optimization — AI systems continuously adjusting manufacturing parameters to maximize efficiency and minimize waste
- Revised EU Emissions Trading System (ETS) — Tighter carbon caps and higher carbon prices creating stronger financial incentives for industrial decarbonization
- Carbon Border Adjustment Mechanism (CBAM) — A carbon tariff on imports from countries with less stringent climate policies, protecting European industrial competitiveness while incentivizing global decarbonization
- Revised Energy Efficiency Directive — Binding energy efficiency targets for industrial facilities
The strategy identifies 14 industrial ecosystems — from automotive to health to energy — as priority areas for policy intervention, investment, and regulatory support.
Important Funding Mechanisms for European Industry
The EU deploys several major funding instruments to support industrial development and transformation:
These funding mechanisms represent an unprecedented level of public investment in European industrial transformation, creating significant opportunities for companies positioned to align with EU strategic priorities.
State Aid and Competition Policy
One of the most complex dimensions of European industrial policy is the tension between EU competition rules — which restrict member state subsidies to individual companies — and the growing recognition that strategic industrial policy sometimes requires targeted public support. The COVID-19 pandemic and subsequent energy crisis led to significant temporary relaxations of state aid rules, with lasting implications for how European governments support their industrial sectors.
The EU’s Important Projects of Common European Interest (IPCEI) mechanism has emerged as a key tool for enabling coordinated, cross-border public investment in strategic industrial sectors including batteries, hydrogen, microelectronics, and cloud computing.
—
Digital Transformation of European Industry
Industry 4.0 and the Smart Factory Revolution
The fourth industrial revolution — characterized by the integration of cyber-physical systems, the Internet of Things (IoT), artificial intelligence, and advanced robotics — is transforming European manufacturing at a fundamental level. Germany coined the term “Industrie 4.0” in 2011, and European manufacturers have been at the forefront of implementing these technologies across their production systems.
Smart factories equipped with connected sensors, real-time data analytics, and autonomous robotic systems are achieving productivity improvements of 15-30% compared to conventional manufacturing facilities. Companies such as Siemens, Bosch, ABB, and Schneider Electric are not only implementing these technologies in their own operations but are also global leaders in providing Industry 4.0 solutions to manufacturers worldwide.
Artificial Intelligence in European Manufacturing
Artificial intelligence is rapidly moving from experimental to mainstream in European industrial applications. Key use cases include:
The EU’s AI Act, which entered into force in 2024, establishes a regulatory framework for AI in industrial applications, creating both compliance requirements and a competitive advantage for European manufacturers in global markets where trustworthy AI is increasingly valued.
The Role of Digital Twins
Digital twin technology — creating virtual replicas of physical industrial assets, processes, and systems — is emerging as one of the most powerful tools in the European industrial digital transformation toolkit. Airbus uses digital twins to optimize aircraft manufacturing processes. Siemens applies them to power plant operations. BMW employs digital twins to design and simulate entire factory layouts before physical construction begins.
Digital twins are expected to generate €100 billion in value for European industry by 2030, according to estimates from the European Commission’s Digital Industry Alliance.
—
Sustainability and the Green Industrial Transition
The European Green Deal and Industrial Decarbonization
The European Green Deal, launched in December 2019, commits Europe to becoming the world’s first climate-neutral continent by 2050. For European industry, this represents both the greatest challenge and the greatest opportunity in a generation. Industry accounts for approximately 20% of EU greenhouse gas emissions, making its decarbonization an absolute prerequisite for meeting climate targets.
The Fit for 55 package — a comprehensive set of legislative measures designed to reduce EU emissions by at least 55% by 2030 — includes several provisions with direct industrial implications:
Green Hydrogen: The Industrial Fuel of the Future
Green hydrogen — produced by electrolyzing water using renewable electricity — is widely recognized as the key enabling technology for decarbonizing industrial processes that cannot be easily electrified, including steel production, cement manufacturing, and chemical synthesis.
The European Hydrogen Strategy targets 10 million tonnes of domestic green hydrogen production by 2030, supported by a €430 billion investment program. Major industrial hydrogen projects are underway across Germany, the Netherlands, Spain, and Portugal, positioning Europe as a global leader in the emerging hydrogen economy.
Circular Economy and Industrial Symbiosis
The transition to a circular economy — in which industrial waste becomes a resource for other processes — is gaining significant momentum across European industry. The EU’s Circular Economy Action Plan sets ambitious targets for reducing industrial waste, increasing recycling rates, and designing products for durability and end-of-life recovery.
Industrial symbiosis — where companies in geographic proximity exchange waste streams and by-products — is being actively promoted through EU-funded programs and national industrial policy initiatives. The Kalundborg industrial symbiosis network in Denmark, often cited as the world’s most advanced example of industrial ecology, provides a compelling model for how European industrial clusters can dramatically reduce resource consumption and environmental impact.
—
Challenges Facing European Industry
Energy Costs and Supply Security
The energy crisis triggered by Russia’s invasion of Ukraine in 2022 exposed a critical vulnerability in the European industrial model: dependence on cheap Russian natural gas. Energy-intensive industries including chemicals, steel, aluminum, glass, and ceramics faced existential cost pressures as natural gas prices surged to unprecedented levels.
While energy prices have moderated since their 2022 peak, European industrial energy costs remain significantly higher than in the United States, China, or the Middle East. Addressing this structural competitive disadvantage — through accelerated renewable energy deployment, energy efficiency investment, and strategic energy storage — is one of the most urgent priorities for European industrial policy.
Skills Shortages and the Workforce Challenge
European industry faces a growing skills crisis. The combination of demographic aging, insufficient STEM education output, and the rapid pace of technological change is creating significant talent shortages across key industrial sectors. Estimates suggest that European industry will need an additional 1 million skilled workers in digital and green technologies by 2030 to achieve its transformation objectives.
Addressing this challenge requires coordinated action across education systems, vocational training programs, immigration policy, and workplace learning initiatives. The EU’s Pact for Skills, launched in 2020, aims to mobilize public and private investment in reskilling and upskilling European workers, with a particular focus on industrial green and digital transitions.
Global Competition and Strategic Dependencies
European industry faces intensifying competition from both established rivals — particularly in North America and Japan — and fast-growing challengers in China, South Korea, and Southeast Asia. In several strategically important sectors, including solar panels, batteries, and rare earth processing, European industry has developed significant dependencies on non-European suppliers.
The EU’s Critical Raw Materials Act and Net-Zero Industry Act, both adopted in 2024, represent major policy responses to these strategic vulnerabilities, setting targets for domestic production of critical materials and clean energy technologies.
—
Regional Industrial Clusters: The Heartbeat of European Manufacturing
Germany: The Industrial Powerhouse
Germany remains the undisputed industrial heart of Europe. With a manufacturing sector contributing approximately 23% of GDP — the highest proportion among major European economies — Germany’s industrial model is built around the famous Mittelstand: thousands of medium-sized, often family-owned companies that are global leaders in specialized industrial niches.
Baden-Württemberg, Bavaria, and North Rhine-Westphalia are Germany’s three most industrially intensive states, hosting world-class clusters in automotive, mechanical engineering, chemicals, and electronics. Germany’s dual vocational education system, which combines classroom learning with workplace apprenticeships, is widely recognized as a model for developing the skilled workforce that advanced manufacturing requires.
Italy: Design, Precision, and Industrial Districts
Italy’s industrial landscape is characterized by its extraordinary network of specialized industrial districts (distretti industriali) — geographic concentrations of small and medium enterprises that collectively achieve world-class competitiveness in sectors including fashion, furniture, ceramics, food processing, packaging machinery, and precision engineering.
The Po Valley, stretching from Turin through Milan to Venice, contains one of Europe’s densest concentrations of industrial activity. Italy is also home to world-class capabilities in luxury goods manufacturing, motorsport engineering, and specialized mechanical systems.
France: Strategic Industries and State-Led Champions
France has historically pursued a more state-directed approach to industrial policy than Germany or Italy, nurturing national champions in aerospace (Airbus, Safran, Thales), energy (TotalEnergies, EDF), transportation (Alstom), and luxury goods (LVMH, Hermès). This model has produced some of Europe’s most globally competitive industrial companies, though it has also been criticized for sometimes prioritizing national prestige over economic efficiency.
France’s “France 2030” industrial investment plan commits €54 billion to reindustrializing the French economy, with priority investments in electric vehicles, green aviation, nuclear energy, quantum computing, and biotechnology.
Eastern Europe: The Rising Industrial Tier
Poland, the Czech Republic, Slovakia, Hungary, and Romania have emerged as major industrial production locations over the past three decades, attracting significant foreign direct investment from Western European and Asian companies seeking competitive manufacturing bases within the European Union.
These countries have developed particular strengths in automotive manufacturing, electronics assembly, and machinery production. The region benefits from a combination of skilled workforces, competitive labor costs, improving infrastructure, and proximity to Western European markets. Poland has become Europe’s sixth-largest economy and a major manufacturing hub, while the Czech Republic boasts the highest industrial share of GDP of any EU member state.
The ongoing integration of Eastern European industrial capacity into pan-European supply chains represents one of the most significant structural developments in Europa Industria over the past generation.
—
Future Outlook: The Next Decade of Europa Industria
Megatrends Shaping European Industry
Several powerful megatrends will define the trajectory of European industry over the coming decade:
Decarbonization will accelerate from a compliance imperative to a competitive differentiator, with early movers in green industrial processes gaining significant market advantages. The carbon border adjustment mechanism will reshape global trade flows, potentially triggering a wave of industrial decarbonization investment beyond Europe’s borders.
Digitalization will continue to permeate every aspect of industrial operations, with artificial intelligence, edge computing, and advanced connectivity enabling levels of automation and optimization that were unimaginable a decade ago. The industrial metaverse — combining digital twins, augmented reality, and collaborative platforms — will transform how products are designed, tested, manufactured, and serviced.
Demographic change will intensify competition for talent, forcing industrial companies to invest heavily in automation, workforce development, and workplace innovation. The retirement of the baby boom generation will create both challenges and opportunities for industrial knowledge transfer.
Geopolitical fragmentation will drive continued emphasis on supply chain resilience and strategic autonomy, with European industry diversifying suppliers, building strategic inventories, and developing domestic production capacity for critical technologies and materials.
Strategic Priorities for European Industrial Competitiveness
To maintain and strengthen its global position, European industry must focus on several strategic priorities:
Invest